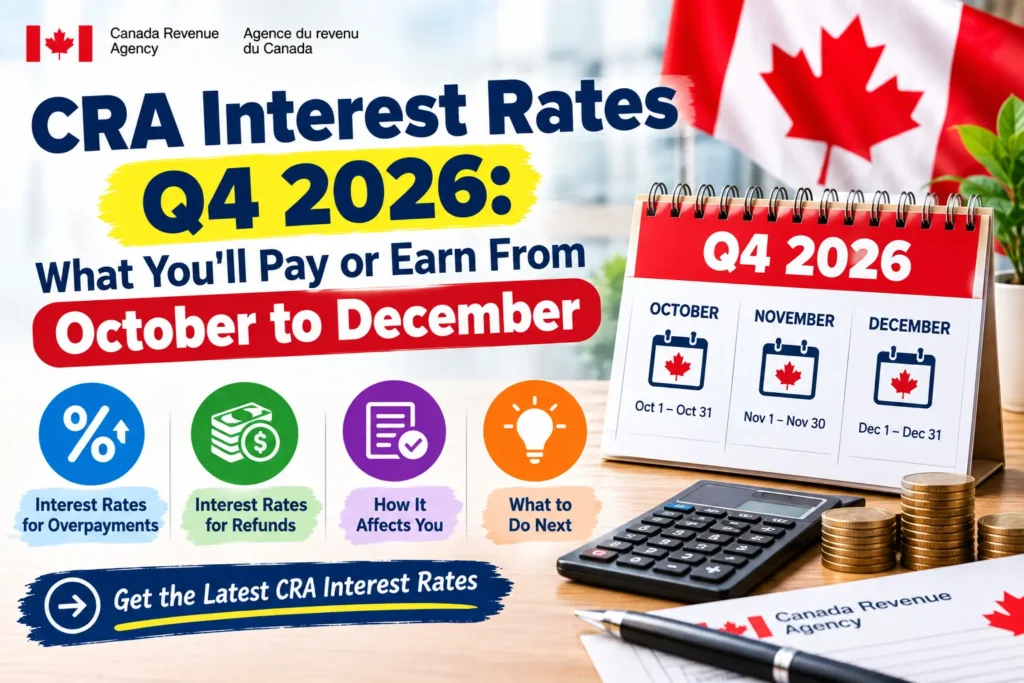
If you owe money to the CRA, or the CRA owes money to you, the rate that applies depends entirely on which quarter you’re in. The CRA interest rates Q4 2026 are now confirmed for the October 1 to December 31 period, and while most figures are holding steady, knowing the exact numbers matters if you’re carrying a tax balance, waiting on a refund, managing a family loan, or running payroll for a small business.
CRA Interest Rates Q4 2026 at a Glance
| Rate Type | Q4 2026 (Oct 1 – Dec 31) |
|---|---|
| Overdue taxes, CPP contributions, EI premiums | 7% |
| Non-corporate taxpayer overpayments (individual refunds) | 5% |
| Corporate taxpayer overpayments | 3% |
| Taxable benefits on interest-free/low-interest loans (the “prescribed rate”) | 3% |
| Corporate pertinent loans or indebtedness | 6.29% |
These rates are set by the CRA and apply to any amount owed to the agency, or owed by the agency to individuals and corporations, during this specific three-month window. They’re published roughly a month before each quarter begins, so businesses and accountants can plan around them in advance.
What Each Rate Actually Means for You
If you owe the CRA money (7%): This is the rate charged on overdue income tax, CPP contributions, and EI premiums. If you have a balance owing from a previous tax year, or you’re behind on instalment payments, this is the rate compounding on what you owe. It applies daily on a compounding basis, not as a flat annual charge, so a balance left unpaid grows faster than a simple 7%-a-year calculation might suggest.
If the CRA owes you money (5%): This applies to non-corporate taxpayer overpayments — in plain terms, if you’re an individual waiting on a refund the CRA hasn’t yet issued, this is the rate you’d be paid on it, though this typically only becomes relevant in specific reassessment or dispute situations rather than a standard, on-time refund.
If you’re a corporation waiting on a refund (3%): Corporate taxpayer overpayments are paid out at a notably lower rate than the individual overpayment rate — 3% versus 5% — which is worth knowing if you run a business through a corporation rather than as a sole proprietor.
If you have an employer or shareholder loan (3%): This is the “prescribed rate,” used to calculate the taxable benefit on interest-free or low-interest loans from an employer, and it’s also the rate commonly used for family income-splitting loan arrangements between spouses or other family members.
If you’re a corporation with a pertinent loan or indebtedness (6.29%): This more specialized rate applies to certain cross-border or related-party corporate lending arrangements, and it moves independently of the standard prescribed rate.
Why the Overdue Rate Is Always Higher Than the Prescribed Rate
There’s a consistent relationship behind these numbers: the rate charged on overdue tax is always the base prescribed rate plus 4 percentage points. With the prescribed rate at 3% for Q4 2026, the overdue tax rate lands at exactly 7% — the same math the CRA has applied consistently across recent quarters. This 4-point gap has held steady for years, so once you know the prescribed rate for any given quarter, you can calculate the overdue rate yourself without waiting for the CRA to publish it separately.
Rates Have Been Stable for a While
The 3% prescribed rate for Q4 2026 marks the sixth consecutive quarter at that level, based on the average yield on 90-day Government of Canada Treasury bills from the first month of the preceding quarter, rounded up to the nearest whole percentage point. If you’ve been holding off on setting up a family income-splitting loan while waiting for rates to shift, this quarter doesn’t change that calculation — the rate is identical to what it’s been for well over a year.
For context, these rates have moved quite a bit over the past several years. During the third quarter of 2020, the prescribed rate sat at just 1%, with the overdue rate at 5%. Rates climbed steadily from 2022 onward as broader interest rates rose, before settling back down to the current 3% level. Understanding this history helps put “record high” or “record low” headlines about CRA rates into perspective — the current 3%/7% split is roughly in the middle of where these rates have sat over the past decade.
A Practical Example: Family Income-Splitting Loans
Here’s how the prescribed rate actually gets used in a common tax-planning scenario. Say a higher-income spouse lends $200,000 to a lower-income spouse at the prescribed rate, and the lower-income spouse invests it to earn a return.
- At a 3% prescribed rate, the lower-income spouse owes $6,000 a year in interest back to the higher-income spouse.
- Provided that interest is actually paid (by January 30 of the following year, every year, without exception), any investment income earned above that $6,000 interest cost is taxed in the lower-income spouse’s hands — typically at a lower marginal rate than the higher-income spouse would have paid on it directly.
- If the investment only earns, say, $4,000 in a weak year, the strategy actually costs money that year rather than saving it, since the interest owed exceeds the return generated.
This is exactly why the “stable rate” context matters: at a low, unchanging 3%, the bar for this strategy to pay off is lower than it would be at a higher prescribed rate, but it still depends on genuinely earning more from the investment than the loan costs.
What This Means If You Have an Outstanding Tax Debt
At 7% compounding daily on overdue amounts, a balance owing doesn’t sit still — it grows every day it remains unpaid, and the effective annual cost ends up slightly above the stated 7% because of daily compounding. If you’re behind on tax instalments or have a balance from a prior year, this is a good moment to check your current standing directly rather than letting it accumulate further. See our guide on CRA Installment Payments Explained if you’re managing instalments specifically, and our guide on how to pay the CRA online if you’re ready to settle a balance directly.
Where to Check Your Own Account
Your CRA My Account shows your current balance, any interest that’s accrued, and your instalment schedule if applicable. If you haven’t set up your account yet, our CRA My Account 2026 guide walks through registration and every major feature, including how to review notices and correspondence tied to any balance owing.
If You’re Disputing a Balance
Interest continues to accrue on a disputed balance while a dispute is in progress, unless the CRA specifically agrees to hold collection action. If you’re contesting a reassessment or a benefit repayment determination, understanding that the clock doesn’t automatically stop is worth factoring into how quickly you pursue a resolution. See our guide on the CRA CERB Repayment Dispute process if your specific situation involves a pandemic-benefit repayment demand.
Conclusion
The CRA interest rates Q4 2026 hold steady across the board, with the prescribed rate unchanged at 3% for a sixth straight quarter and the overdue tax rate sitting at 7%. Whether you’re managing a family loan, sitting on a tax balance, or simply want to understand what the CRA would charge or pay in this specific window, these are the confirmed figures through December 31, 2026 — worth bookmarking, since the next set of rates gets announced roughly a month before Q1 2027 begins.
Frequently Asked Questions
What are the CRA interest rates for Q4 2026?
7% on overdue taxes, CPP contributions, and EI premiums; 5% on non-corporate overpayments; 3% on corporate overpayments and taxable benefits on employer loans; and 6.29% on corporate pertinent loans.
Did the CRA prescribed rate change for Q4 2026?
No. The prescribed rate remains at 3%, the sixth consecutive quarter at that level.
How is the CRA overdue tax rate calculated?
It’s always the base prescribed rate plus 4 percentage points. At a 3% prescribed rate, the overdue tax rate is 7%.
Does a family loan I set up earlier change rate every quarter?
No. A prescribed-rate loan generally locks in the rate that was in effect when the loan was set up, even if the CRA’s published rate changes in later quarters.
Does interest keep accruing while I’m disputing a CRA balance?
Generally yes, unless the CRA specifically agrees to pause collection action during your dispute, so resolving a dispute quickly can limit how much interest accumulates.
When does the CRA announce the next quarter’s rates?
Typically about one month before the new quarter begins, so Q1 2027 rates are usually announced in late 2026.
Where can I find the official CRA interest rate release?
Directly on canada.ca, under the CRA’s prescribed interest rates page, updated each quarter.
This article is for informational purposes only and does not constitute tax or financial advice. Confirm current rates directly through canada.ca before making tax or loan decisions.
Stay updated with the latest Canada government benefits, payment dates, and CRA news — explore more guides at Benefits Pulse Hub.